HOME / 2015 READING ROOM
Understand the loan before the deadline
Four guides to payday borrowing, repayment costs and alternatives.
A short loan can change a monthly budget quickly. These four guides examine what a payday loan costs, when repayment is due, what can go wrong after a missed payment and which alternatives to compare.
Four questions before borrowing
- 01 — Can a payday loan have no fees?
- 02 — What if you do not have a checking account?
- 03 — How does a payday loan work?
- 04 — What should you check online?
Begin with the full amount due
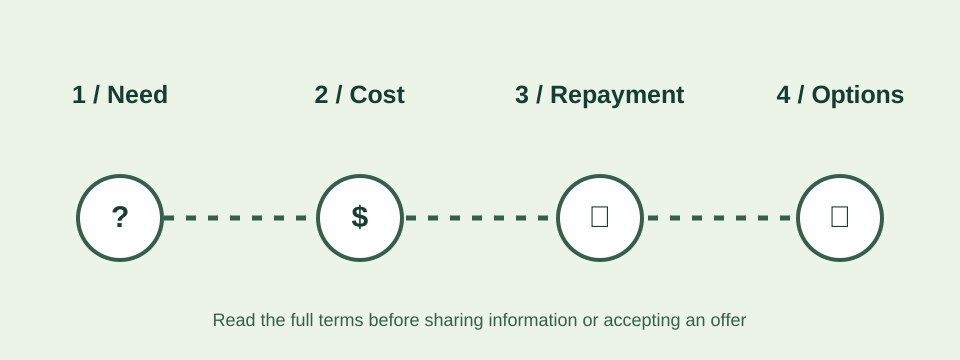
An urgent expense can make an advertised approval speed look like the only fact that matters. The repayment amount and date matter just as much. Read how a payday loan works before comparing any offer, then check the online application questions before sharing personal information.
Follow the original topics in a better order
The 2015 site had four articles. This edition brings them into a blog that begins with the borrowing decision, then examines “no fee” language, no-checking-account offers and online forms. The words in an advertisement cannot replace a written agreement. The CFPB’s consumer guide explains costs, repayment and common issues from a primary source.
Featured guides
Begin with the borrowing decision, then examine the terms in more detail.
- 01
How payday loans work
A plain-language sequence for assessing a short-term loan, based on current consumer guidance.
- 02
No-fee payday loans: read the total cost
The historical headline promised no fees; a borrower should check every charge and the amount due.
- 03
Online payday loans: checks before you apply
An online form should not precede clarity about the lender, total cost and data handling.